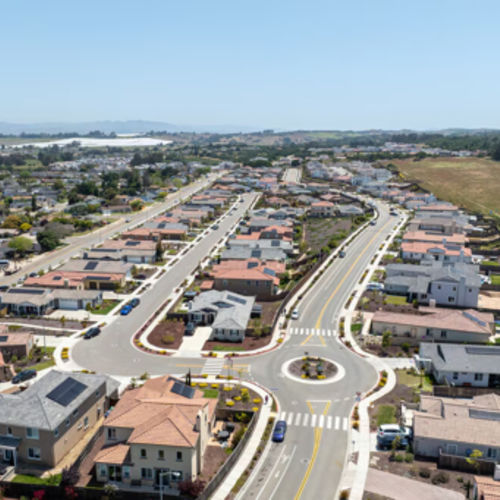
Are you wondering whether help is available to buy your first home in Lompoc? Yes. Qualified first-time buyers may be able to access local and statewide programs that reduce upfront costs through down payment assistance, deferred-payment loans, and closing cost support.
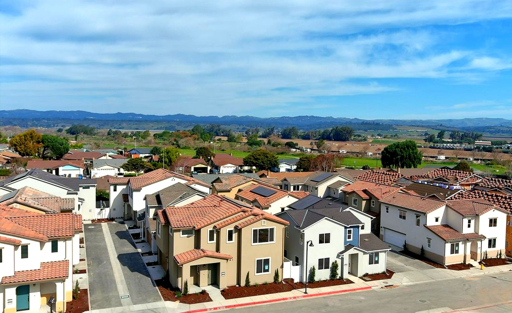
Eligible Lompoc homes may qualify for local first-time buyer assistance.
Buying your first home can feel financially demanding, especially when you are saving for a down payment while also preparing for closing costs. The good news is that Lompoc buyers may have more options than they realize, provided they meet program requirements and work with the appropriate approved lender.
What Assistance Is Available in Lompoc?
The primary local option is the Lompoc Homebuyer Assistance Program (LHAP), administered by the City of Lompoc’s CDBG/Housing Division. It is designed to expand homeownership opportunities by lowering upfront purchase costs and ongoing carrying costs for qualified buyers. The City of Lompoc provides program details and application guidance through its official housing division page.
The Lompoc Homebuyer Assistance Program applies to eligible homes within city limits.
The program is intended for first-time home buyers with low to moderate incomes. Participants must purchase an eligible home within Lompoc city limits and meet the program’s income and property requirements.
Lompoc Homebuyer Assistance Program
Under the City of Lompoc’s published program highlights, eligible participants may receive a deferred-payment assistance loan of up to 18% of the purchase price, not to exceed $153,000. The loan carries a fixed 3% interest rate and a 30-year term.
A key benefit is that the assistance loan has no monthly payments. Repayment is deferred until the earliest of refinancing the first mortgage, selling the property, transferring title, default, or the 30-year maturity date.
The program also offers a closing cost grant of up to $7,500 for qualified buyers. Eligible properties are owner-occupied, single-family homes within Lompoc city limits that are on a permanent foundation and have an individual deed.
Who May Qualify?
To be considered for LHAP, you generally need to:
Be a first-time home buyer.
Have household income at or below 120% of the Area Median Income.
Purchase a home located within Lompoc city limits.
Buy an eligible owner-occupied, single-family property.
Apply through a City-approved first mortgage lender.
Program rules, income limits, and underwriting standards can change, so confirm current requirements directly with the City or an approved lender before relying on any figure. The City of Lompoc provides its Homebuyer Assistance Program details and application guidance through its official housing division page.
Statewide Help Through CalHFA
Even if a buyer does not qualify for LHAP, California offers statewide assistance through the California Housing Finance Agency, commonly called CalHFA. Its MyHome Assistance Program provides a deferred-payment junior loan that can be used for down payment and/or closing costs. CalHFA’s official MyHome page explains the program’s eligibility rules and application process.
Down payment assistance can help qualified buyers reach the closing table.
For CalHFA government loans backed by FHA, MyHome offers assistance of up to the lesser of 3.5% of the purchase price or appraised value. For CalHFA conventional loans, the assistance is up to the lesser of 3% of the purchase price or appraised value.
CalHFA does not lend directly to consumers. Buyers apply through a CalHFA-approved lender, and eligibility depends on factors such as first-time buyer status, income limits, primary-residence occupancy, and completion of approved homebuyer education.
CalHFA Requirements to Know
CalHFA’s MyHome program generally requires that you:
Be a first-time home buyer.
Occupy the property as your primary residence.
Meet CalHFA income limits.
Complete homebuyer education and counseling through an eligible provider.
Work with a CalHFA-approved lender.
The program can be used with eligible single-family, one-unit residences, including approved condominiums and PUDs. Manufactured housing may also be permitted, subject to program guidelines.
You can review the current eligibility rules and application process on the official CalHFA MyHome Assistance Program page.
Why Homebuyer Education Matters
Homebuyer education is not just a box to check. It can help you understand mortgage terms, budgeting, credit, the purchase process, and the long-term responsibilities of ownership.
Homebuyer education helps first-time buyers prepare for ownership responsibilities.
For CalHFA programs, at least one occupying first-time borrower must complete homebuyer education and counseling. CalHFA accepts its designated online course or live education through NeighborWorks America or a HUD-approved housing counseling agency.
HUD-approved counselors can provide guidance tailored to your situation, including pre-purchase counseling and homebuyer education. You can find California counseling resources through HUD’s California housing page.
How Assistance Affects Closing Costs
Down payment assistance can reduce the cash needed at the beginning of the transaction, but buyers should still plan for closing costs. These may include lender fees, title-related charges, escrow items, prepaid taxes or insurance, and other transaction expenses.
Reviewing closing costs early can help buyers avoid surprises before settlement.
The Consumer Financial Protection Bureau explains that buyers receive a Closing Disclosure at least three business days before closing. This document itemizes loan terms and closing fees, helping you understand the total cash needed to close. The CFPB’s closing process guide provides additional detail on what to expect.
Assistance programs may cover some of these expenses, but coverage depends on the specific program and lender guidelines. Ask your lender to provide a clear estimate of what assistance will cover and what you will still need to bring to closing.
Steps to Take Before Applying
A little preparation can make the process smoother and help you determine which program best fits your situation.
Review your household income. Both LHAP and CalHFA programs have income requirements, and the applicable limits depend on program rules and household circumstances.
Confirm first-time buyer status. Program definitions matter, so ask the lender or counseling agency how your prior homeownership history affects eligibility.
Gather financial documents. CalHFA recommends having pay stubs, bank statements, employment history, and prior tax returns available when speaking with a loan officer.
Contact an approved lender. For LHAP, the City directs applicants to a City-approved first mortgage lender. For CalHFA, you must use a CalHFA-approved lender.
Complete required education early. If you pursue CalHFA assistance, completing the required homebuyer education before you are under contract can help avoid delays.
Compare total monthly costs. Look beyond the down payment and consider taxes, insurance, maintenance, utilities, and any deferred assistance loan terms.
Common Questions From Lompoc Buyers
Can assistance be combined with an FHA loan?
It may be possible, depending on the program and lender guidelines. CalHFA’s MyHome program can be used with eligible CalHFA government loans, including FHA-backed financing, while LHAP has its own first-mortgage and underwriting requirements.
Does assistance mean I do not need any cash?
Not necessarily. Assistance may reduce the amount needed for a down payment or closing costs, but you may still need funds for earnest money, inspections, remaining closing costs, moving expenses, or reserves. The CFPB notes that the cash needed at closing reflects your down payment, deposits already made, and closing-related costs.
Can I use assistance anywhere in Santa Barbara County?
LHAP is specifically for homes located within Lompoc city limits. CalHFA programs are statewide, but eligibility, property type, income limits, and lender participation still apply.
Final Takeaway
First-time buyers in Lompoc may be able to reduce the upfront cost of purchasing a home through the City’s LHAP program or statewide CalHFA assistance. The most important step is to speak with an approved lender early, confirm current eligibility requirements, and complete any required homebuyer education before making an offer.
For local guidance on Lompoc homes, neighborhoods, and the buying process, visit The Francia Team. Jason Francia - The Francia Team helps Central Coast California buyers understand their options and move forward with confidence.
Ready to Explore Your Options?
If you are considering buying your first home in Lompoc, start by reviewing your eligibility for local and statewide assistance. Then connect with a lender and a local real estate professional who can help you understand how assistance may fit into your purchase plan.
Contact The Francia Team to discuss your Lompoc home search and next steps toward homeownership.
This mode enables people with epilepsy to use the website safely by eliminating the risk of seizures that result from flashing or blinking animations and risky color combinations.
Visually Impaired Mode
Improves website's visuals
This mode adjusts the website for the convenience of users with visual impairments such as Degrading Eyesight, Tunnel Vision, Cataract, Glaucoma, and others.
Cognitive Disability Mode
Helps to focus on specific content
This mode provides different assistive options to help users with cognitive impairments such as Dyslexia, Autism, CVA, and others, to focus on the essential elements of the website more easily.
ADHD Friendly Mode
Reduces distractions and improve focus
This mode helps users with ADHD and Neurodevelopmental disorders to read, browse, and focus on the main website elements more easily while significantly reducing distractions.
Blindness Mode
Allows using the site with your screen-reader
This mode configures the website to be compatible with screen-readers such as JAWS, NVDA, VoiceOver, and TalkBack. A screen-reader is software for blind users that is installed on a computer and smartphone, and websites must be compatible with it.
Online Dictionary
Readable Experience
Content Scaling
Default
Text Magnifier
Readable Font
Dyslexia Friendly
Highlight Titles
Highlight Links
Font Sizing
Default
Line Height
Default
Letter Spacing
Default
Left Aligned
Center Aligned
Right Aligned
Visually Pleasing Experience
Dark Contrast
Light Contrast
Monochrome
High Contrast
High Saturation
Low Saturation
Adjust Text Colors
Adjust Title Colors
Adjust Background Colors
Easy Orientation
Mute Sounds
Hide Images
Virtual Keyboard
Reading Guide
Stop Animations
Reading Mask
Highlight Hover
Highlight Focus
Big Black Cursor
Big White Cursor
Text to Speech
Navigation Keys
Accessibility Statement
franciateam.com
October 22, 2026
Compliance status
We firmly believe that the internet should be available and accessible to anyone, and are committed to providing a website that is accessible to the widest possible audience,
regardless of circumstance and ability.
To fulfill this, we aim to adhere as strictly as possible to the World Wide Web Consortium’s (W3C) Web Content Accessibility Guidelines 2.1 (WCAG 2.1) at the AA level.
These guidelines explain how to make web content accessible to people with a wide array of disabilities. Complying with those guidelines helps us ensure that the website is accessible
to all people: blind people, people with motor impairments, visual impairment, cognitive disabilities, and more.
This website utilizes various technologies that are meant to make it as accessible as possible at all times. We utilize an accessibility interface that allows persons with specific
disabilities to adjust the website’s UI (user interface) and design it to their personal needs.
Additionally, the website utilizes an AI-based application that runs in the background and optimizes its accessibility level constantly. This application remediates the website’s HTML,
adapts Its functionality and behavior for screen-readers used by the blind users, and for keyboard functions used by individuals with motor impairments.
If you’ve found a malfunction or have ideas for improvement, we’ll be happy to hear from you. You can reach out to the website’s operators by using the following email [email protected]
Screen-reader and keyboard navigation
Our website implements the ARIA attributes (Accessible Rich Internet Applications) technique, alongside various different behavioral changes, to ensure blind users visiting with
screen-readers are able to read, comprehend, and enjoy the website’s functions. As soon as a user with a screen-reader enters your site, they immediately receive
a prompt to enter the Screen-Reader Profile so they can browse and operate your site effectively. Here’s how our website covers some of the most important screen-reader requirements,
alongside console screenshots of code examples:
Screen-reader optimization: we run a background process that learns the website’s components from top to bottom, to ensure ongoing compliance even when updating the website.
In this process, we provide screen-readers with meaningful data using the ARIA set of attributes. For example, we provide accurate form labels;
descriptions for actionable icons (social media icons, search icons, cart icons, etc.); validation guidance for form inputs; element roles such as buttons, menus, modal dialogues (popups),
and others. Additionally, the background process scans all of the website’s images and provides an accurate and meaningful image-object-recognition-based description as an ALT (alternate text) tag
for images that are not described. It will also extract texts that are embedded within the image, using an OCR (optical character recognition) technology.
To turn on screen-reader adjustments at any time, users need only to press the Alt+1 keyboard combination. Screen-reader users also get automatic announcements to turn the Screen-reader mode on
as soon as they enter the website.
These adjustments are compatible with all popular screen readers, including JAWS and NVDA.
Keyboard navigation optimization: The background process also adjusts the website’s HTML, and adds various behaviors using JavaScript code to make the website operable by the keyboard. This includes the ability to navigate the website using the Tab and Shift+Tab keys, operate dropdowns with the arrow keys, close them with Esc, trigger buttons and links using the Enter key, navigate between radio and checkbox elements using the arrow keys, and fill them in with the Spacebar or Enter key.Additionally, keyboard users will find quick-navigation and content-skip menus, available at any time by clicking Alt+1, or as the first elements of the site while navigating with the keyboard. The background process also handles triggered popups by moving the keyboard focus towards them as soon as they appear, and not allow the focus drift outside of it.
Users can also use shortcuts such as “M” (menus), “H” (headings), “F” (forms), “B” (buttons), and “G” (graphics) to jump to specific elements.
Disability profiles supported in our website
Epilepsy Safe Mode: this profile enables people with epilepsy to use the website safely by eliminating the risk of seizures that result from flashing or blinking animations and risky color combinations.
Visually Impaired Mode: this mode adjusts the website for the convenience of users with visual impairments such as Degrading Eyesight, Tunnel Vision, Cataract, Glaucoma, and others.
Cognitive Disability Mode: this mode provides different assistive options to help users with cognitive impairments such as Dyslexia, Autism, CVA, and others, to focus on the essential elements of the website more easily.
ADHD Friendly Mode: this mode helps users with ADHD and Neurodevelopmental disorders to read, browse, and focus on the main website elements more easily while significantly reducing distractions.
Blindness Mode: this mode configures the website to be compatible with screen-readers such as JAWS, NVDA, VoiceOver, and TalkBack. A screen-reader is software for blind users that is installed on a computer and smartphone, and websites must be compatible with it.
Keyboard Navigation Profile (Motor-Impaired): this profile enables motor-impaired persons to operate the website using the keyboard Tab, Shift+Tab, and the Enter keys. Users can also use shortcuts such as “M” (menus), “H” (headings), “F” (forms), “B” (buttons), and “G” (graphics) to jump to specific elements.
Additional UI, design, and readability adjustments
Font adjustments – users, can increase and decrease its size, change its family (type), adjust the spacing, alignment, line height, and more.
Color adjustments – users can select various color contrast profiles such as light, dark, inverted, and monochrome. Additionally, users can swap color schemes of titles, texts, and backgrounds, with over 7 different coloring options.
Animations – epileptic users can stop all running animations with the click of a button. Animations controlled by the interface include videos, GIFs, and CSS flashing transitions.
Content highlighting – users can choose to emphasize important elements such as links and titles. They can also choose to highlight focused or hovered elements only.
Audio muting – users with hearing devices may experience headaches or other issues due to automatic audio playing. This option lets users mute the entire website instantly.
Cognitive disorders – we utilize a search engine that is linked to Wikipedia and Wiktionary, allowing people with cognitive disorders to decipher meanings of phrases, initials, slang, and others.
Additional functions – we provide users the option to change cursor color and size, use a printing mode, enable a virtual keyboard, and many other functions.
Browser and assistive technology compatibility
We aim to support the widest array of browsers and assistive technologies as possible, so our users can choose the best fitting tools for them, with as few limitations as possible. Therefore, we have worked very hard to be able to support all major systems that comprise over 95% of the user market share including Google Chrome, Mozilla Firefox, Apple Safari, Opera and Microsoft Edge, JAWS and NVDA (screen readers), both for Windows and for MAC users.
Notes, comments, and feedback
Despite our very best efforts to allow anybody to adjust the website to their needs, there may still be pages or sections that are not fully accessible, are in the process of becoming accessible, or are lacking an adequate technological solution to make them accessible. Still, we are continually improving our accessibility, adding, updating and improving its options and features, and developing and adopting new technologies. All this is meant to reach the optimal level of accessibility, following technological advancements. For any assistance, please reach out to [email protected]