
You've been browsing homes for sale in Guadalupe CA, and now you're wondering what paycheck it actually takes to buy one. It's the right question to ask before you tour a single house.
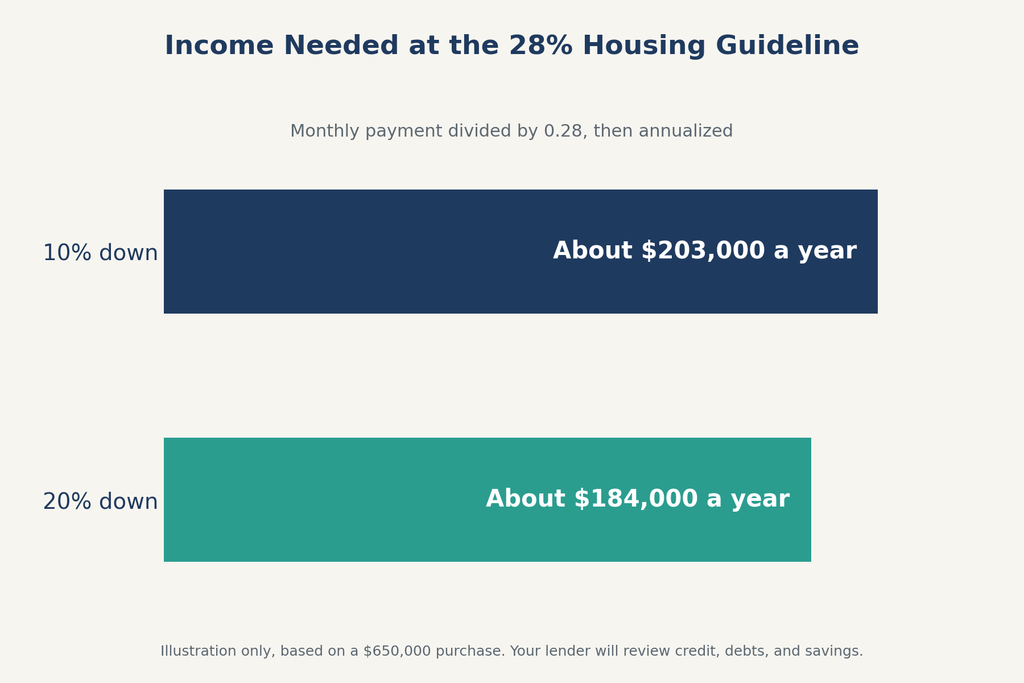
The short answer: A common lender guideline is to keep your housing payment near 28% of your gross monthly income. For a $650,000 home with 10% down at a 7.25% rate, that works out to roughly $203,000 a year. Your own number will shift with the price, your down payment, your rate, and your other debts.
How do lenders decide how much income you need?
Lenders look at two ratios. The first compares your housing costs to your gross monthly income, and many use 28% as a starting guideline. The second compares all of your monthly debts to that same income.
To estimate your income target, divide your expected monthly housing payment by 0.28. That gives you the gross monthly income that fits the guideline.
Treat it as a starting point, not a pass or fail test. Lenders also weigh credit, savings, and job history.
What goes into your monthly payment?
Your payment is more than the loan itself. It typically includes four parts:
- Principal and interest on the loan
- Property taxes
- Homeowners insurance
- Mortgage insurance, if your down payment is under 20%
Many buyers only budget for the first item, which is why the income they need often surprises them.
What does the math look like for a Guadalupe purchase?
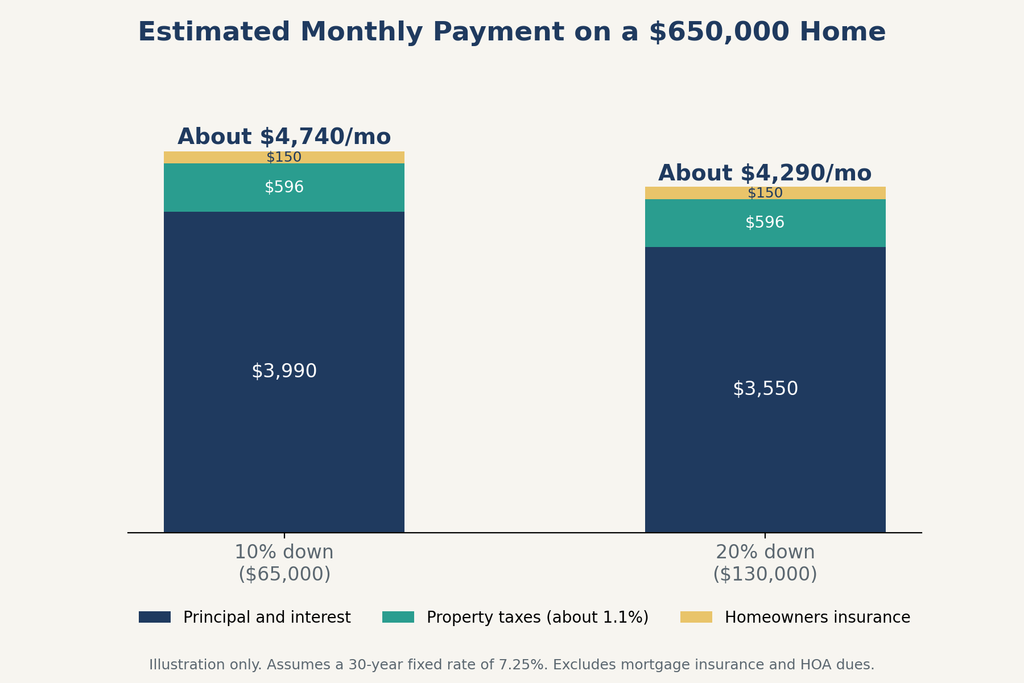
Here is an illustration, not a market statistic or a lender quote. Assume a $650,000 purchase price, a 30-year fixed rate of 7.25%, property taxes of about 1.1% of the price, and $150 a month for insurance. Mortgage insurance and HOA dues are not included.
- 10% down ($65,000): Principal and interest is about $3,990 a month. With taxes and insurance, the total is about $4,740, which points to an income of roughly $203,000 a year.
- 20% down ($130,000): Principal and interest is about $3,550 a month. With taxes and insurance, the total is about $4,290, which points to an income of roughly $184,000 a year.
A larger down payment lowers the income you need. It also costs more cash up front, so it's worth weighing both sides.
How much do interest rates change the answer?
Rates have a big effect. Freddie Mac's weekly survey, tracked by the Federal Reserve Bank of St. Louis, showed 30-year fixed averages above 7% in mid-October 2026.
On a loan this size, a one-point change in the rate moves your monthly payment by several hundred dollars. That can change the income you need by tens of thousands of dollars a year.
Rates also change week to week. Ask a lender for current numbers before you decide on a price range.
Do your other debts matter as much as your income?
Yes. Your car payment, student loans, and credit card minimums all count against you. The Consumer Financial Protection Bureau explains how debt-to-income ratio works and why lenders look at it.
The 43% figure you often hear is no longer a hard cap. Research from the St. Louis Fed notes that the CFPB moved to a price-based standard in 2021, though many lenders still treat 43% as a rule of thumb.
Paying down a balance before you apply can lower your ratio. In some cases it helps more than a raise would.
Can down payment help change the income you need?
It can. First-time buyers may qualify for assistance through CalHFA's MyHome Assistance Program, a deferred-payment loan that works with a CalHFA first mortgage. Income limits vary by county, and homebuyer education is required.
Programs like this can reduce the cash you need at closing. Eligibility rules change, so confirm the details with a CalHFA-approved lender.
What should you know about property taxes after you buy?
California's system works differently from most states. Under Proposition 13, the base rate is 1% of assessed value plus voter-approved local charges, and the State Board of Equalization explains that annual increases in assessed value are generally limited to 2% unless the property changes ownership or has new construction.
As a new buyer, your assessed value will usually reset to your purchase price. Plan your budget around your own purchase, not a neighbor's tax bill.
The bottom line
There isn't one income number for Guadalupe. There is a method: estimate your full monthly payment, divide it by 0.28, then check the result against your other debts.
Use real quotes for your rate and insurance. Then you'll know your range before you fall in love with a house.
Find Out What You Can Afford in Guadalupe
If you'd like to talk through your numbers, Jason Francia - The Francia Team can help you build a realistic budget and search homes in Guadalupe and the surrounding Central Coast. Visit franciateam.com to get started.
Check out this article next
